Quick answer: Your interest rate sets your monthly payment. APR adds lender fees, points and mortgage insurance to that rate and spreads them over all 30 years. If you expect to sell or refinance in about 5 years, those upfront costs fall on far fewer payments than APR assumes. For a shorter horizon, compare the "In 5 Years" line on page 3 of each Loan Estimate.
You have two Loan Estimates. One has the lower APR. The other has the lower closing costs. The better deal depends on how long you will keep the loan, and APR does not account for that.
This guide explains rate vs. APR on a home loan: what each number includes, what it leaves out, and which one to use for the time you expect to keep the loan.
What Is APR vs. Interest Rate?

APR Assumes You Keep the Loan 30 Years
APR treats your upfront costs as if you paid them off slowly over the whole loan term. On a 30-year mortgage, that means spreading them across 360 monthly payments.
Most people don't keep the same mortgage that long. They sell, move or refinance. When that happens, the upfront costs you paid at closing don't get the full 30 years to "spread out." You paid all of them, and you got the lower rate for only part of the term.
Here is what that means in practice:
- A quote with high points and a low rate can show the lower APR.
- The same quote can cost you more if you leave the loan in 5 years.
- The shorter you keep the loan, the more upfront costs matter and the less the rate matters.
The Loan Estimate already gives you a better number for a short horizon. On page 3, under Comparisons, the In 5 Years line shows two figures: the total you will have paid in principal, interest, mortgage insurance and loan costs in the first 5 years, and how much principal you will have paid off (12 CFR 1026.37(l)). Compare that line across quotes when you expect to move or refinance within about 5 years.
Run your numbers: see how much principal you pay off by month 60 with our amortization calculator.
What Your Interest Rate Covers
Your interest rate (also called the note rate) is the percentage the lender charges each year on the balance you owe. It sets your monthly principal-and-interest payment. It does not include any fees.
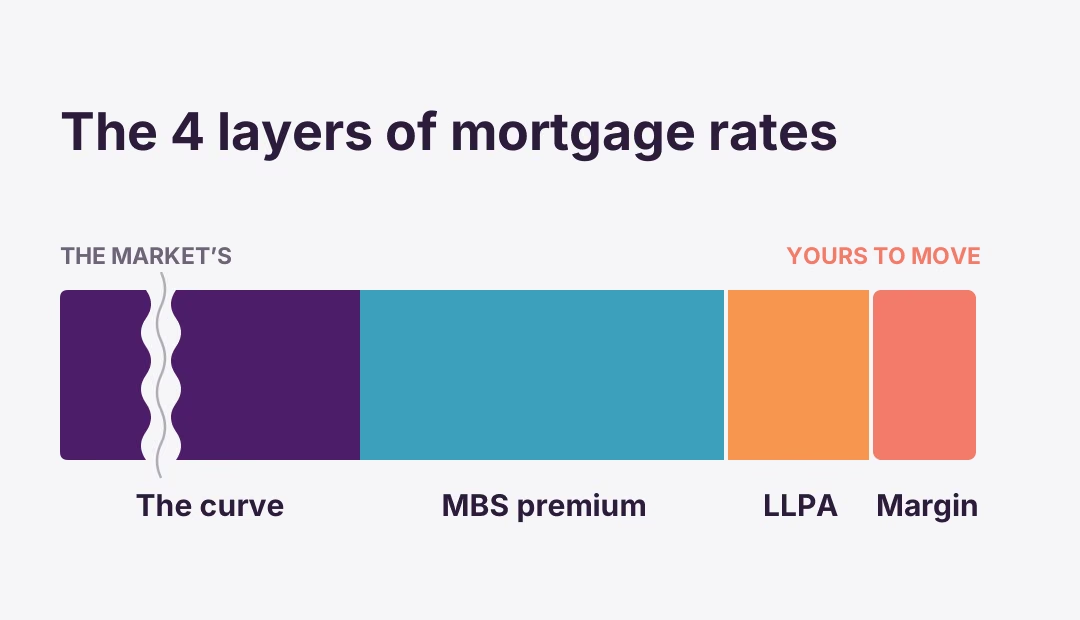
If you keep the loan for a long time, the rate is the main driver of what you pay. To understand why one lender's rate differs from another's, see how mortgage rates are determined.
Two borrowers can also get different rates from the same lender on the same day. Fannie Mae and Freddie Mac add risk fees based on credit score and down payment, and those fees usually show up as a higher rate. See LLPAs explained.
What APR Adds, and What It Leaves Out
APR (annual percentage rate) is a federally required disclosure under the Truth in Lending Act. It converts the rate plus certain upfront charges into one yearly percentage, so two loans can be compared on one number. The CFPB describes APR as the rate plus points, broker fees and other charges (CFPB: rate vs. APR).
Usually included in APR
- Origination charges: the lender's or broker's own fees for making the loan
- Discount points: upfront interest you pay to get a lower rate. One point equals 1% of the loan amount.
- Broker compensation when you pay it
- Mortgage insurance premiums
- Prepaid interest from closing to your first payment
Usually left out of APR
- Appraisal fee
- Credit report fee
- Title insurance and settlement fees
- Property taxes and homeowners insurance
These lists follow the finance charge rules in Regulation Z, 12 CFR 1026.4. Because third-party charges are mostly left out, two quotes with the same APR can still need different amounts of cash at closing. Read Section A of each Loan Estimate to see the lender's own fees. Our guide to origination charges walks through that section line by line.
Worked Example: Lower APR, Higher 5-Year Cost
Illustrative example, not a rate quote or offer. Figures are rounded and exclude taxes, insurance and third-party costs, which are assumed to be the same for both quotes.
Both quotes are for a $400,000, 30-year fixed loan (360 monthly payments). APRs treat all upfront loan costs as prepaid finance charges.

Quote A has the lower APR. It also has the lower payment, by $130 a month. On APR alone, Quote A looks like the clear choice.
After 5 years, Quote B has cost you $1,970 less. Quote A charged you $12,000 more at closing. Its lower rate needs about 6 years to earn that money back.
Here is how the gap changes with time:

"Cost" here means the interest you paid plus the upfront loan costs. It leaves out principal, because principal is your own equity.
Altgage perspective: As a broker, Altgage can shop multiple wholesale lenders. Whoever you work with, ask for the same loan priced with and without points, and work out the break-even month.
Break-Even: If You Won't Keep the Loan 30 Years
The break-even point is the month when a lower-rate, higher-cost quote catches up to a higher-rate, lower-cost one. Before that month, the cheaper-upfront quote wins. After it, the lower-rate quote wins.
In the example, break-even comes at about month 72. If you expect to sell or refinance before then, Quote B costs less. If you expect to stay longer, Quote A costs less.
A quick estimate: divide the extra upfront cost by the monthly payment savings. Here that is $12,000 divided by $130, about 92 months. That shortcut runs long, because it ignores the extra principal the lower rate pays off each month. For a closer figure, compare total interest plus upfront costs month by month, as the table above does.
Run your numbers: find the break-even month for points on your own loan with our mortgage points calculator.
Pro tip: Before you pay points, decide how long you realistically expect to keep the loan. Then check whether the break-even month falls inside that window. Our guide to mortgage points covers how points are priced.
What Is a "Good" APR?
A good APR sits close to the note rate for your loan type, credit score and down payment. A wide gap between the two means you are paying a lot upfront. That is a signal to look closely at Section A of the Loan Estimate.
There is no single good APR for everyone. The rate you qualify for depends on your credit score, down payment, property type and loan program. To check the APR gap on your own quotes, use the quote comparison tool.
How to Compare APR Across Your Quotes
Use APR as one check among several, and only after the quotes are comparable.
- Match the basics. Same loan amount, loan type, term and lock period. An APR on a 30-year fixed can't be compared fairly with one on an ARM or a 15-year loan.
- Pull quotes on the same day. Pricing changes daily. Quotes from different days aren't comparable.
- Compare the rate and the points together. A lower rate bought with points is a different product than a lower rate with no points.
- Check APR. Within matching quotes, a lower APR usually means lower total cost over the full term.
- Check the "In 5 Years" line. If you may move or refinance within about 5 years, this figure matters more than APR.
- Check cash to close. Page 1 shows what you need to bring on closing day.
Golden rule: Compare quotes with the same loan amount, term and lock period, pulled the same day. Otherwise the APRs don't measure the same thing.
You can line up these figures side by side with the Altgage quote comparison tool. For the full shopping process, read how to shop for a mortgage.
Frequently Asked Questions
What is APR vs. interest rate on a home loan?
The interest rate is the yearly cost of borrowing the loan amount, and it sets your monthly payment. APR is a yearly figure that adds lender fees, discount points and mortgage insurance to that rate, spread over the full loan term. Use the rate to see your payment and APR to compare total cost between quotes.
Is APR or interest rate more important?
It depends on how long you keep the loan. The interest rate sets your monthly payment. APR shows total borrowing cost if you keep the loan for its full term. If you expect to sell or refinance within a few years, upfront fees matter more than APR suggests, so compare break-even points.
Is APR useful if I plan to sell in 5 years?
Less so. APR spreads upfront costs over the full loan term, usually 30 years. If you sell in 5 years, you pay all of those costs but get the lower rate for only 60 months. Compare the "In 5 Years" figure on page 3 of each Loan Estimate instead.
Why is my APR higher than my interest rate?
APR adds lender fees, discount points and mortgage insurance to the rate. The larger those charges, the wider the gap. A large gap is a reason to read Section A of your Loan Estimate closely.
Can APR be lower than the interest rate?
Yes. When a lender credit is larger than the finance charges, the APR can come in below the note rate. That usually means you accepted a higher rate in exchange for lower closing costs.
Which one sets my monthly payment?
The interest rate. APR does not change your payment. It is a disclosure figure for comparing total cost across loans.
Does APR include closing costs?
Some of them. Lender fees and points are included. Most third-party charges, such as the appraisal and title insurance, are not. Two quotes with equal APRs can still require different cash at closing.
APR vs. APY: what is the difference?
APR is the yearly cost of a loan, including certain fees. APY is the yearly return on savings, including compounding. Mortgages are disclosed with APR.
The Bottom Line
The interest rate sets your payment. APR adds certain fees and assumes you keep the loan for its full term. Neither one accounts for how long you will keep the loan, which often decides which quote costs less.
If you plan to stay a long time, a lower APR usually points to the cheaper loan. If you may move or refinance within about 5 years, compare the "In 5 Years" line and the break-even month before you pay points.
Have Loan Estimates in hand? Grade your Loan Estimate to compare rate, points, fees and 5-year cost side by side, or get pre-approved.
Related Reading
- Mortgage Points Calculator
- Amortization Calculator
- How to Shop for a Mortgage
- How Mortgage Rates Are Determined: The Four Layers
- Mortgage Points Explained
- How to Read a Loan Estimate
- Should I Lock My Mortgage Rate Today?
- Grade your Loan Estimate
This article is educational and is not financial advice. Altgage Inc., NMLS #2447252, is a mortgage broker licensed in California, Colorado, Florida, Georgia, Massachusetts and Texas. This is not a commitment to lend. Rates, fees and program rules change; verify current terms with a licensed loan officer.